When Your Supplier Becomes Your Banker
SpaceX is raising forty billion dollars to buy chips from the company that owns a stake in SpaceX.
Read it twice, because it is not a riddle. The chips are Nvidia's. The stake is Nvidia's. The money is borrowed, and it is reported to be secured by the very chips it buys.
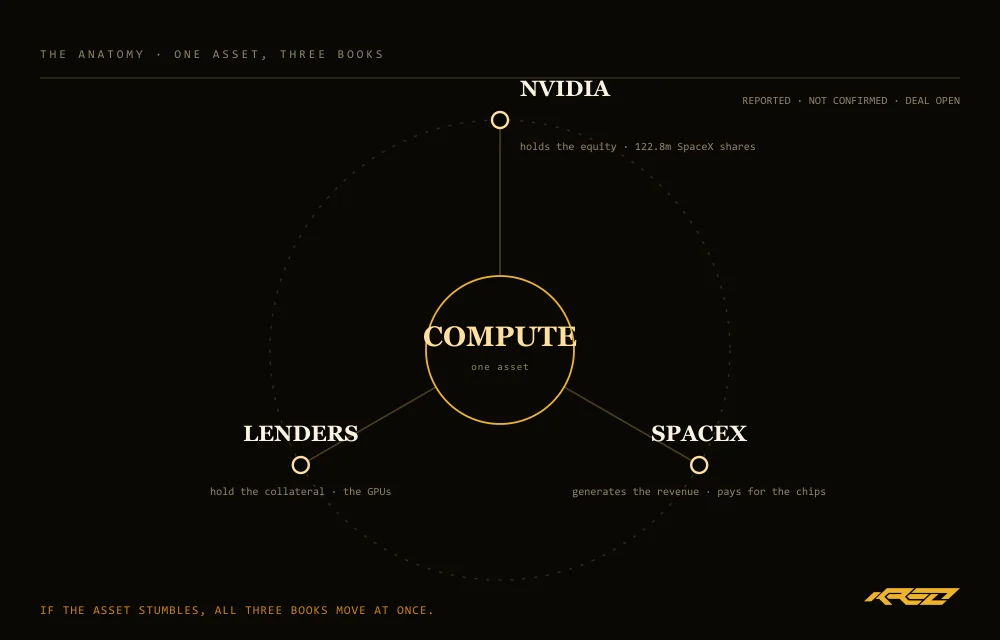
That is this week's news. The interesting part is the machine underneath it, and the machine has a name. When your supplier becomes your banker, the supplier's revenue and your own solvency start riding the same asset. In a rising market the arrangement hums. In a falling one both sides give way together, because there is no diversification inside a loop. There is only itself.
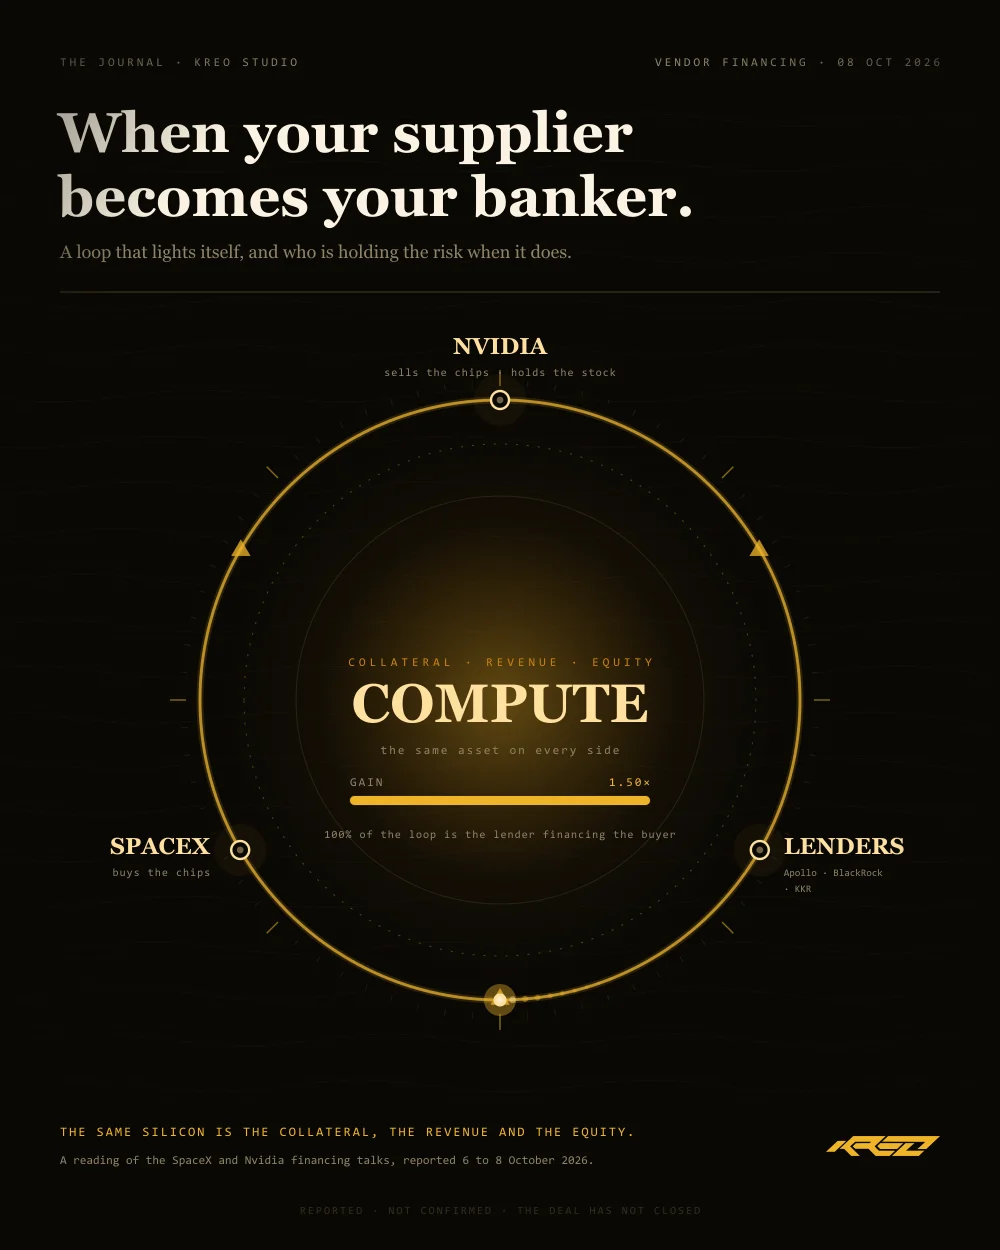
The loop, drawn plainly
Nvidia sells the chips. Nvidia also holds the buyer's stock, a stake of about twenty-one billion dollars that arrived when its ten billion dollar investment in xAI folded into SpaceX. And Nvidia has stood up the financing: in August it signed agreements with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to mobilise over five hundred billion dollars, so its own customers can borrow to buy its product. Goldman's David Solomon called it "a market for credit backed by NVIDIA compute".
Broadcom is running the same play: a sixty billion dollar package for Anthropic's build-out, and early talks to finance OpenAI's custom chip. Everyone is financing everyone. When one asset is the collateral, the revenue and the equity at once, a wobble in its price compresses the whole ledger in a single motion.
Interactive · the loop
Open the loop, or close it.
One deal, two shapes. Flick it to watch what the lender is really lending against.
GAIN 1.00×1.50×
Two companies, one sale.One shared fate.
Why anyone would do it
The bull case is not stupid. Compute is scarce, useful and unusually fungible: a GPU rented to one lab can serve another, and it keeps a resale value. Borrowing at investment-grade rates to lock in supply before a shortage is, taken alone, rational. Jensen Huang has the honest framing.
"In AI, compute is revenue." Jensen Huang, Nvidia.
Nor is SpaceX a fragile borrower. It went public in June in the largest listing on record, raised twenty-five billion dollars in bonds two weeks later, and is reported to be holding roughly a hundred billion in cash.
The honest counterpoint
Here is where I step off. Morgan Stanley puts the external financing AI infrastructure will need by 2028 at about 1.5 trillion dollars, with perhaps three hundred billion of investment-grade bonds this year alone. That is a buildout leaving cash behind for credit, and credit reprices from the ground up. SpaceX's existing debt already trades near junk levels. If the price of a GPU, or of renting one, softens, the collateral and the income soften together, and a loop becomes a spiral.
I want to be exact about what I know. I did not read the loan documents; they are not public. The forty billion figure is reported by the Financial Times and corroborated by Reuters and CNBC, the deal has not closed, and the companies would not comment. I have used both sides of this market myself, GPUs rented by the hour and a box under the desk, so I read the numbers from the buyer's seat, not the bank's. What would change my mind: a chip rental market that stays liquid through a real downturn.
Readout: what is confirmed, and what is not
- Confirmed (NVIDIA, 10 August 2026): agreements with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to mobilise over $500bn of third-party capital; Jensen Huang said "In AI, compute is revenue"; David Solomon called it "a market for credit backed by NVIDIA compute".
- Confirmed (NVIDIA Q2 13F via CNBC, 14 August 2026): Nvidia holds 122.8m SpaceX Class A shares worth about $21bn at the end of the second quarter, from its $10bn xAI investment folded into SpaceX.
- Reported (Financial Times via Reuters, CNBC and US News, 6-7 October 2026): SpaceX is seeking about $40bn, roughly $10bn bank loans and $30bn investment-grade debt, led by Apollo, with PIMCO in talks; GPUs are likely to be used as collateral; the transaction is expected to close in 2027.
- Reported (Reuters, 8 October 2026): SpaceX holds roughly $100bn in cash, which raises the question of why it is borrowing at all.
- Reported (Bloomberg via Digitimes, 8 October 2026): Broadcom arranged a $60bn debt package for Anthropic and has held early talks to finance OpenAI's custom chip purchase.
- Not confirmed: the final terms, the true collateral, and any independent benchmark of the asset's value. The deal has not closed and the companies would not comment.
If you are weighing a build-out against a credit line and want a second pair of eyes on where the risk actually sits, email brandon@kreostudio.co.uk.
Sources & references
- SpaceX seeks $40 billion financing to buy Nvidia chips, Reuters, 6 October 2026.
- Apollo, banks in talks to finance SpaceX’s $40 billion Nvidia GPU purchase, CNBC, 7 October 2026.
- SpaceX Seeks $40 Billion to Buy Nvidia Chips, FT Reports, Reuters via US News, 6 October 2026.
- Nvidia discloses $21 billion stake in SpaceX at end of second quarter, CNBC, 14 August 2026.
- NVIDIA Partners With Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR..., NVIDIA Newsroom, 10 August 2026.
- Broadcom in early talks to finance OpenAI’s custom chip purchases, Digitimes via BAB News, 8 October 2026.
Reader signal
Was this useful?
Work with KREO Studio
AI engineering, data science and design architecture, from Plymouth to the wider UK.
Next Article